
Why Does Dave Mention That You Don’t Need Short-Term Disability Insurance?
Have you heard Dave Ramsey talk about disability insurance? You may be asking yourself, “why does Dave Ramsey recommend not buying short-term disability insurance?”You see, when it comes to disability, it’s going to stop your paycheck and with short term disability insurance you are paid a part of your salary while you are unable to work.
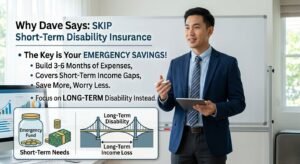
If you’re wondering why does dave mention that you don’t need short-term disability insurance?, The important point is that Dave’s suggestion applies to short-term financial risks of the sort he describes. In his world, a well-equipped emergency fund is a stash of cash to cover a short-term loss of income; a long-term disability is something quite different, because the long-term loss of income it implies is so significant that savings can hardly be expected to make up for it.
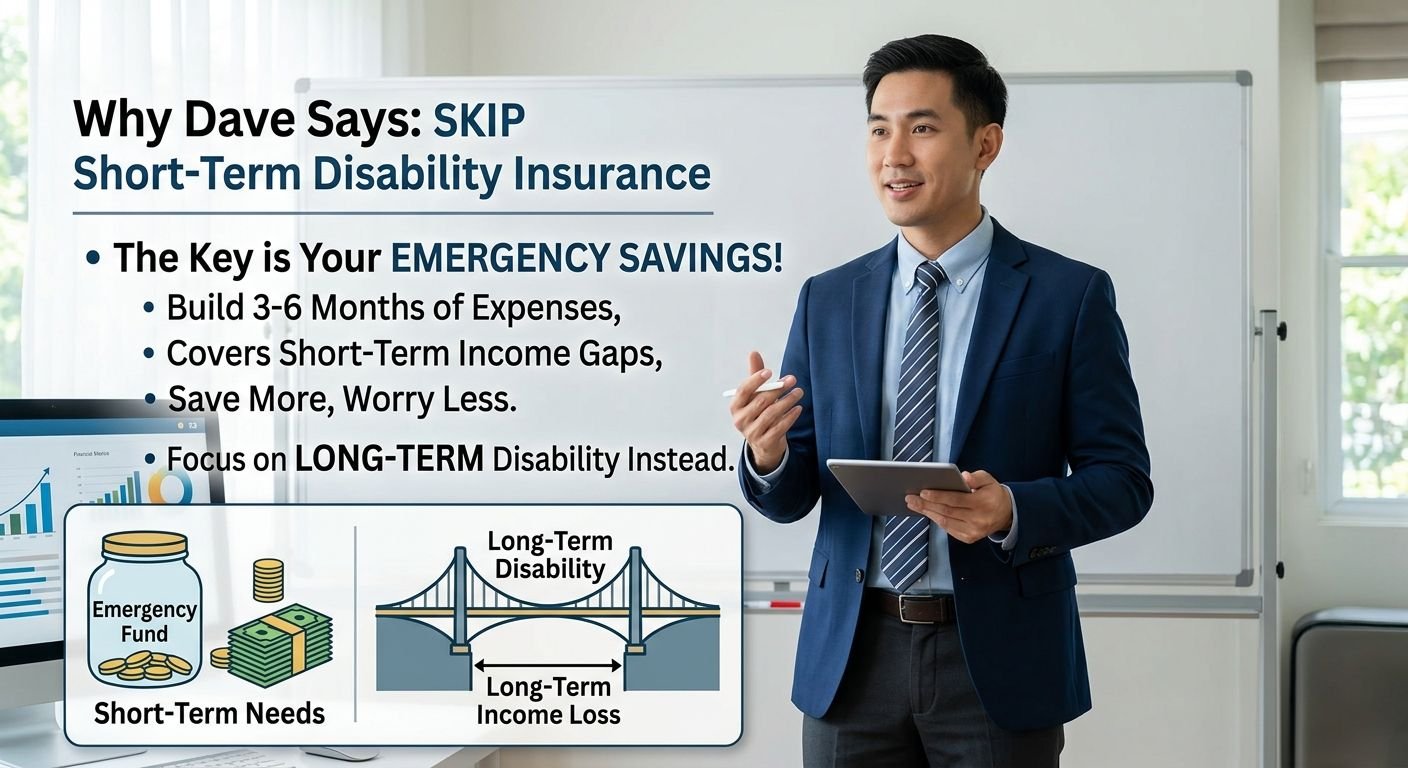
Ramsey’s present advice states it doesn’t suggest paid short-term disability protection unless it’s offered as a free perk for workers. It instead recommends a fully paid emergency fund for shorter gaps and recommends long-term disability coverage in the event of a long-term income loss.
That said, short-term disability insurance isn’t without value to everyone. Other financial-planning strategies could reach a different answer, based on a person’s savings, benefits through work, income stability, and household expenses.
This is the logic that supports Dave’s argument and the most essential qualifications to grasp.
Why Does Dave Mention That You Don’t Need Short-Term Disability Insurance?
Dave’s basic argument is about self-insuring a short-term risk.
If you’re wondering why does dave mention that you don’t need short-term disability insurance?, Short-term disability coverage tends to be designed to fund a portion of your income for the finite time you miss work due to a covered sickness or injury. Rather than purchase an insurance company to lever that relatively short-term risk, Dave keeps enough emergency savings to handle the disruption himself.
The written advice from Ramsey itself states that – unless the employer is directly paying for short-term coverage – those who go with its method are able to tap a three- to six-month cushion of cash for a brief time off of work.
The logic can be summarized like this:
Short-term income interruption → emergency savings
Long-term loss of earning ability → long-term disability insurance
That distinction is the foundation of the recommendation.
It’s also crucial to remember that this is a money philosophy and risk management strategy; it’s not an all-encompassing insurance regulation. It might not be a good idea to get short-term insurance if you have the cash, paid time off, an employer benefit, or a true plan.
How an Emergency Fund Fits Into Dave’s Reasoning
An emergency fund is designed to provide cash when an unexpected and necessary financial resource problem occurs.
If you’re wondering why does dave mention that you don’t need short-term disability insurance?, At the moment, Ramsey advises to save up an emergency fund that is completely funded at three to six months’ worth of expenses. This is considered Baby Step 3. It is defined as a financial cushion to buffer against significant surprises – loss of job, medical expenses, etc.
That’s significant because Dave’s short-term disability argument isn’t really about dismissing the potential for lost income. It’s about planning for that eventuality differently.
Let’s assume that a worker is out of commission for a short period of time and is without a paycheck. If that worker has enough liquid assets on hand to pay fixed expenses for a few months, then the emergency fund is able to help that worker out in the meantime.
The savings are not disability insurance. They merely provide the individual with a financial cushion, but do not trigger the filing of an insurance claim.
Example: Using Savings for a Temporary Income Gap
Think of someone with $4,000 in unavoidable monthly expenses and six months of emergency savings.
They have around $24,000 for emergencies that would qualify.
In the event of an unforeseen hiatus resulting in a temporary loss of income, the emergency fund might be able to sustain household expenses.
And this is what Dave is talking about when he says we self-insure the short-term risk.
The key caveat is that an emergency fund is not an endless replacement for your income. A major or long-term disability may wipe out savings, which is one of the reasons Dave distinguishes between short-term and long-term coverage.
What Does “Self-Insuring” Mean?
Self-insuring simply means retaining enough personal financial resources to absorb a particular risk instead of purchasing insurance specifically for that risk.
For example, someone might choose not to buy a separate insurance policy for a relatively small financial risk because they have enough cash to handle it.
The concept becomes more significant when applied to short-term disability.
Instead of:
Premiums → insurance company → potential short-term benefit
Dave’s framework emphasizes:
Savings → emergency fund → temporary income gap
This approach also explains why emergency savings are so important in the broader Baby Steps system.
But self-insuring only makes sense so long as the individual really has access to sufficient savings. An individual with a dearth of emergency funds would be taking a very different financial risk than someone who had a few months’ worth of necessary expenses.
How the Baby Steps Connect to Short-Term Disability
The connection becomes clearer when you look at Dave’s broader financial system.
If you’re wondering why does dave mention that you don’t need short-term disability insurance?, In Baby Steps, Ramsey starts with a starter emergency fund, followed by debt repayment, and then suggests a big emergency fund. The latest Baby Steps guidance from Ramsey places Baby Step 3 as saving three to six months of expenses once non-mortgage debt is paid off.
That increased cash cushion is also why, says Ramsey, he does not consider paid short-term disability as a requirement of his program.
The progression is essentially:
Starter emergency savings → debt reduction → fully funded emergency savings → protection against larger financial risks
Once a household has a substantial emergency reserve, it has some ability to absorb temporary disruptions without immediately replacing every short-term risk with an insurance policy.
If you’re wondering why does dave mention that you don’t need short-term disability insurance?, Ramsey’s current insurance guidance makes this distinction explicit: short-term disability is generally not recommended unless it is a free employee benefit, while long-term disability is considered important because it protects income beyond what an emergency fund can reasonably cover.
Short-Term vs. Long-Term Disability Insurance
Understanding the difference between the two types of coverage is essential.
| Feature | Short-Term Disability | Long-Term Disability |
| Main purpose | Temporary income replacement | Extended income protection |
| Coverage period | Usually limited to a relatively short period | Can continue for years, depending on the policy |
| Main financial concern | Temporary loss of earnings | Prolonged loss of earning ability |
| Dave/Ramsey approach | Emergency savings may handle the risk | Insurance is strongly emphasized |
| Employer coverage | May be available | May be available |
| Policy terms | Vary by plan | Vary by plan |
Each policy is going to offer different benefit percentages, different waiting periods before coverage kicks in, different definitions of what constitutes a disability, and various lengths of time that coverage is provided for. Ramsey’s comparison of their own policies can give general ranges, but the policy will be what determines this.
That difference is important. Someone comparing insurance policies might see the document itself, rather than assuming that all short-term and long-term disability plans are identical.
Why Does Dave Still Recommend Long-Term Disability Insurance?
This is where Dave’s position can easily be misunderstood.
The argument is not that disability insurance is unnecessary.
Instead, Dave distinguishes between a temporary financial interruption and a prolonged loss of earning power.
If you’re wondering why does dave mention that you don’t need short-term disability insurance?,A short-term problem might last several weeks or months. A serious long-term disability could prevent someone from working for years, making how disability insurance can replace lost income an important consideration. One such case may be covered by your emergency fund, but you could be left empty-handed in the other.
According to Ramsey’s latest guidance, long-term disability insurance is necessary because it replaces income if you become ill or injured and can’t work for an extended time. In her recent Baby Steps guidance on insurance, she explains long-term disability covers income loss after the emergency fund phase.
This produces a simple risk-management distinction:
Small or temporary financial risk: potentially absorb it with savings.
Large or prolonged financial risk: consider transferring the risk through insurance.
That is the reasoning behind the different treatment of short-term and long-term disability.
What If Your Employer Offers Short-Term Disability for Free?
This happens to be among the most common exceptions to know about.
Ramsey’s current guidance states that it does not recommend short-term disability insurance when you have to buy it, but it does when it’s given as a free employee benefit.
Why does that matter?
Since there is no extra employee premium when this equation changes.
Let’s take an illustration: Suppose an employer offers short-term disability as a benefit. In that case, the employee is not making a decision between:
Paying for insurance vs. saving the money.
Possibly, the use can be already built into work.
But even if you get past all that, the right policy makes a difference. Employees need to know waiting periods, benefits, length of time for which they will be paid, eligibility guidelines and taxability.
A “free” benefit can still have limitations.
When Might Short-Term Disability Insurance Still Be Valuable?
This is not to be mistaken for a general financial adage.
There are also some financial-planning points of view that prioritize short-term disability coverage, especially if a household couldn’t live comfortably for a couple of months.
Situations that can change the analysis include:
- Limited emergency savings
- High essential monthly expenses
- Little or no paid sick leave
- No employer disability benefits
- Self-employment or freelance work
- A household that relies primarily on a single source of income
- Limited access to other forms of income replacement
Depending on the context, Money Management International may also refer to short-term disability as a discussion of savings, employment types, and a short term absence of income.
What you need to know, however, is not that either side is right for everyone, but that the degree of financial risk you are willing and able to tolerate is what is relevant.
A person with large amount of cash savings does not have the same income risk in the short-term as an individual with very little cash buffer.
Emergency Fund vs. Short-Term Disability Insurance
An emergency fund and short-term disability insurance may address some of the same financial problem, but they are not the same product.
| Factor | Emergency Fund | Short-Term Disability Insurance |
| Source of money | Your own savings | Insurance benefits |
| Primary purpose | Broad emergency protection | Covered disability-related income loss |
| Eligibility | No insurance claim required | Must satisfy policy requirements |
| Flexibility | Generally broad | Limited by policy terms |
| Cost | Requires building savings | Requires premiums unless employer-paid |
| Main risk | Savings can be depleted | Claim may not qualify or may have limits |
An emergency fund can generally be used for different qualifying financial emergencies, while disability insurance is tied to the terms of the policy.
That distinction is important when comparing the two.
A Simple Scenario: Two People, Two Different Risk Profiles
Consider two hypothetical workers.
Person A: Strong Emergency Reserve
Person A has:
- Several months of essential expenses saved
- Stable employment
- Access to paid leave
- No major short-term cash-flow problem
Under Dave’s framework, this person may have a strong reason to rely on savings rather than paying separately for short-term disability coverage.
Person B: Limited Savings
Person B has:
- Very little emergency savings
- High fixed expenses
- No paid leave
- No employer disability benefit
A temporary interruption in income could create a much more immediate financial problem.
That does not automatically determine what Person B should purchase. It demonstrates why financial circumstances matter when evaluating the value of insurance.
What Policy Details Should You Check?
Whether someone is considering short-term or long-term disability coverage, the label alone does not tell the whole story.
Important policy details can include:
Elimination Period
This is the waiting period before benefits become payable after a qualifying disability.
Benefit Amount
Policies generally replace only a portion of income rather than the entire paycheck.
Maximum Benefit Period
A short-term policy may provide benefits for a limited period. Long-term policies can have substantially longer benefit periods.
Definition of Disability
The policy’s definition determines when someone qualifies for benefits. Different policies can use different standards.
Employer vs. Individual Coverage
Employer-sponsored coverage and individually purchased policies can have different costs, portability, tax treatment, and terms.
Exclusions and Limitations
Always review the actual policy language rather than assuming a condition or absence from work automatically qualifies.
These details are important because two disability policies can have very different financial effects even when both are called “short-term disability insurance.”
Common Misunderstandings About Dave’s Position
“Dave says disability insurance is unnecessary.”
That is not an accurate summary. His published guidance strongly emphasizes long-term disability protection while treating paid short-term coverage differently.
“An Emergency Fund and Insurance Serve the Same Purpose”
It isn’t. An emergency fund consists of money you have personally set aside in savings.Insurance is a contractual arrangement that can provide benefits when specified conditions are met.
“A three-to-six-month emergency fund guarantees financial security.”
It does not. Ramsey recommends three to six months as its fully funded emergency-fund target, but an emergency fund has a finite balance and cannot necessarily cover every possible event.
“Short-term disability and long-term disability are basically identical.”
They both can replace part of income after a qualifying disability, but their coverage periods, waiting periods, policy definitions, and financial purposes can differ substantially.
“Free Employer-Provided Coverage Is Equivalent to Paid Coverage”
Not necessarily. Ramsey itself makes a distinction between paid short-term coverage and short-term coverage offered free through an employer.
Why This Advice Should Be Viewed in Context
The most sensible interpretation of Dave’s position is as a simple version of a risk-management approach.
His method is to create financial margin, so that less serious emergencies can be covered by savings and insurance is kept to cover only those risks that could potentially inflict much greater financial pain.
This explains the reason for the added U-drive to conserve.
However, every financial plan is unique. The value of the coverage will differ based on the particulars of your employer benefits, savings, income stability, household expenses, paid leave, policy conditions and your own risk preferences.
So the better question is not simply, “Is short-term disability insurance good or bad?”
A more useful question is:
“How would a temporary loss of income affect my finances, and what resources would actually cover that gap?”
That question gets to the underlying issue without assuming that one financial strategy applies equally to everyone.
FAQs
1.Why does Dave mention that you don’t need short-term disability insurance?
Overview for Dave Ramsey Is short-term income loss a risk? Yes, paid short-term disability insurance is not recommended at this time, unless offered to you at no cost by your employer. Dave’s guideline is that short term income loss is a risk you can manage with a sufficient emergency fund.
2.Does Dave Ramsey recommend long-term disability insurance?
Yes. Ramsey’s published guidance places significant emphasis on long-term disability insurance because a prolonged inability to work can create an income loss that an emergency fund may not cover.
3.Can an emergency fund replace short-term disability insurance?
In Dave’s budget an emergency fund can be the short-term cushion rather than a particular short-term disability coverage. Yet, savings and insurance are different tools and an emergency fund has a limited amount.
4.What if my employer provides short-term disability insurance for free?
Ramsey’s current policy leaves out free employee benefits and states to accept the coverage if it’s available free. You’ll want to check the requirements, waiting period, benefits and whether there’s a cap.
5.How much emergency savings does Dave Ramsey recommend?
Ramsey currently recommends a fully funded emergency fund covering three to six months of expenses as Baby Step 3. It also recommends a $1,000 starter emergency fund earlier in the Baby Steps.
6.Is short-term disability insurance always unnecessary?
No. Dave’s recommendation should be understood within his specific financial framework. Other financial-planning approaches may consider short-term disability useful for people with limited savings, high essential expenses, no paid leave, or little access to employer benefits.
7.What is the main difference between short-term and long-term disability insurance?
The most significant difference is the length of time and amounts of income protection covered. Short term protection is for a temporary period where as long term disability protection is for a much longer period of time to compensate for a long time period for loss of your ability to earn an income.
Conclusion
The answer to why does Dave mention that you don’t need short-term disability insurance? comes down to his approach to managing different levels of financial risk.
In the framework of Dave Ramsey, a short-term cash flow gap is a good candidate for an emergency fund that has been well-funded. Short-term disability insurance is less expensive, and instead you save enough money to cover a shorter gap.
You don’t hear a lot about these long term benefits for the same reason you don’t hear a whole lot about long term care: If you can’t work, you might face a financial risk that your savings cannot really address. That’s why we tend to emphasize long-term disability insurance, and usually oppose paid short-term coverage-except for free benefits through your employer.
The bottom line, in a nutshell: Dave’s advice is just one financial model, not a one-size-fits-all guide for anyone. When you get down to figuring out the right answer, you need to take into account emergency savings, employer benefits, job security, necessary expenses, paid time off and the actual details of whatever policy you’re looking at.
The two bits of information should help you understand why he’s recommended it in the first place.